Freightos Baltic: Asia–Europe extends month-long climb on hub congestion as Transpacific holds peak plateau ahead of US port strike deadline
Global east–west container rates diverged in the week to 30 October 2026, as European hub congestion and strike backlogs extended Asia–Europe gains whilst Transpacific benchmarks held near peak plateaus despite cooling post-season demand.
|
Route |
Cost (USD/FEU) |
Changes |
|
Updated on 30 November 2026 |
||
|
Asia – US West Coast |
$ 8,340 |
- |
|
Asia – US East Coast |
$ 9,911 |
▼ 6% |
|
Asia – Northern Europe |
$ 3,595 |
▲ 1% |
|
Asia – Mediterranean |
$ 4,375 |
▲ 3% |
Read more on Freightos
Global east–west container rates diverged in the week to 30 October 2026, as European hub congestion and strike backlogs extended Asia–Europe gains whilst Transpacific benchmarks held near peak plateaus despite cooling post-season demand.
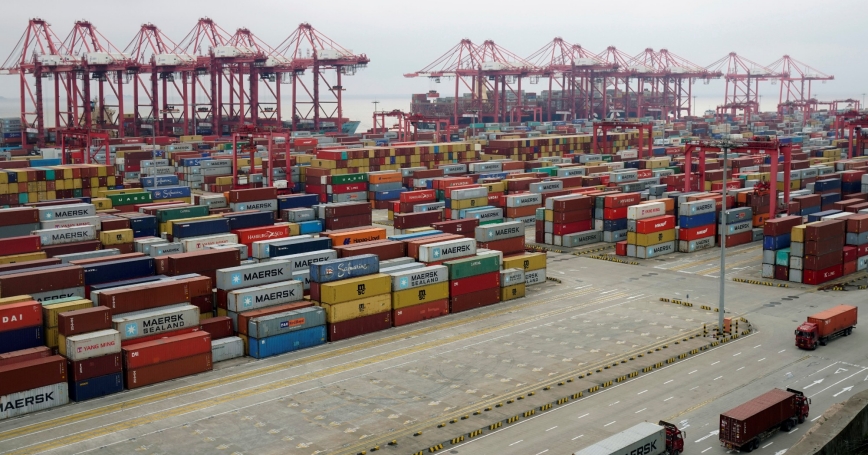
According to the Freightos Baltic Index (FBX), Asia–Mediterranean spot rates rose 3% to $4,375/FEU and Asia–Northern Europe edged up 1% to $3,595/FEU, lifting cumulative past-month gains to 23% and 10%, respectively, despite expanding Red Sea vessel transits. Across the Pacific, Asia–US West Coast prices held flat at $8,340/FEU—maintaining the $8,300/FEU plateau established in September—whilst Asia–US East Coast rates cooled 6% from the prior week’s spike to $9,911/FEU (roughly $9,900/FEU), remaining $200/FEU above levels two weeks ago.
The Europe-bound advance reflects persistent congestion across Northern European hubs and lingering Far East backlogs, compounded by a recent one-day port worker strike across multiple European and international terminals. Liners have scheduled General Rate Increases (GRIs) of $1,000–$1,500/FEU for early November alongside further mid-month hikes, though flat daily rates so far this week leave forwarders sceptical that sluggish post-peak volumes will support additional increases.
Transpacific carriers have similarly tabled early-November GRIs of $2,000–$3,000/FEU, yet daily pricing has stayed flat as the trade enters its seasonal lull. Whilst Asia–Europe rates shed $2,000–$3,000/FEU between July and September to revisit mid-May pre-peak baselines before rebounding in October, Transpacific benchmarks still hold a roughly $5,500/FEU premium over pre-peak levels even after Golden Week. That elevated buffer, paired with a narrow window before pre-Lunar New Year restocking begins, makes a retreat to pre-peak baselines unlikely before demand climbs again.
Labour friction on the US West Coast could further prop up Transpacific pricing as cargo demand cools. Local 26 of the International Longshore and Warehouse Union (ILWU)—representing Los Angeles and Long Beach port watchmen operating under an expired contract since mid-2025—authorised a strike from 1 November before agreeing over the weekend to extend negotiations with federal mediators until 5:00 pm PT on 4 November. Because these watchmen provide mandatory terminal security services, a walkout by the relatively small union would trigger outsized operational disruption across Southern California gateways.
Written by: Aiman Haikal